Compare benefit accounts and reimbursement arrangements, then coordinate the administration they require.
Read the full introduction
SSGI helps employers distinguish insurance from the accounts, reimbursement arrangements, and cafeteria-plan rules that surround it. We coordinate plan design, administrator selection, payroll setup, enrollment communication, and renewal review while the employer and its legal and tax advisers retain formal plan and tax responsibilities.
An HSA belongs to an eligible individual; a health FSA is an employer-sponsored account with plan-specific use rules; an HRA is employer funded; a QSEHRA has separate employer eligibility rules; and a Section 125 plan governs qualifying pre-tax elections. Choosing one begins with the medical plan, employer size, tax objectives, administration capacity, and workforce—not the acronym.
Account comparison
What each arrangement is designed to do
Current federal rules and the governing documents control. SSGI organizes the decision and coordinates qualified administrators and advisers.
HSA
Health Savings Account (HSA)
Ownership
Individually owned
Funding
Eligible individual and/or employer contributions
Portability
The account stays with the individual
An individually owned, portable account generally paired with HSA-eligible high-deductible health coverage. Eligibility can be affected by other coverage, and contribution limits change by year.
FSA
Health Flexible Spending Account (FSA)
Ownership
Employer-sponsored arrangement
Funding
Salary reductions; employer contributions if the plan permits
Portability
Continuation and termination rules follow the plan
An employer-sponsored arrangement funded through salary reductions and, if designed, employer contributions. Election, carryover or grace-period, substantiation, and termination rules follow the plan and federal limits.
HRA
Health Reimbursement Arrangement (HRA)
Ownership
Employer-established reimbursement arrangement
Funding
Employer contributions only
Portability
Post-employment reimbursement depends on plan terms
An employer-funded arrangement reimbursing eligible expenses under written terms. HRA designs vary, and coordination with group or individual coverage is central.
Compare the structure first. Eligibility, permitted contributions and continuation depend on current rules and the governing plan. IRS Publication 969 (opens in a new tab)
Qualified Small Employer HRA (QSEHRA)
A defined-contribution reimbursement path for eligible small employers that generally do not offer a group health plan. Employer eligibility, notice, substantiation, affordability, and Marketplace interactions require careful review.
Section 125 cafeteria plan
The written framework that can permit qualifying employee premium and account elections on a pre-tax basis. It is not insurance, and nondiscrimination, election, and documentation rules matter.
Commuter and other tax-advantaged benefits
Qualified transportation and related benefits may complement the core program. Annual federal limits, eligible expenses, payroll, and local rules should be verified before implementation.
Operations
Implementation details that prevent avoidable friction
The arrangement only works when the plan documents, administrator, payroll, enrollment, and employee instructions agree.
Eligibility and plan-document alignment
Define eligible classes, effective dates, waiting periods, qualifying coverage, reimbursable expenses, election rules, and who has authority to make final determinations.
Payroll and contribution setup
Map employer funding, employee salary reductions, deduction timing, contribution frequency, corrections, and year-end reporting with the payroll and tax teams.
Administrator and substantiation
Confirm claim-substantiation, reimbursement, debit-card, privacy, appeals, data-feed, service, and record-retention responsibilities before launch.
COBRA and leave coordination
Review whether and how each arrangement continues during COBRA, leave, termination, rehire, and other status changes under the plan and current law.
Benefits beyond the renewal
A service team and a platform your people can use.
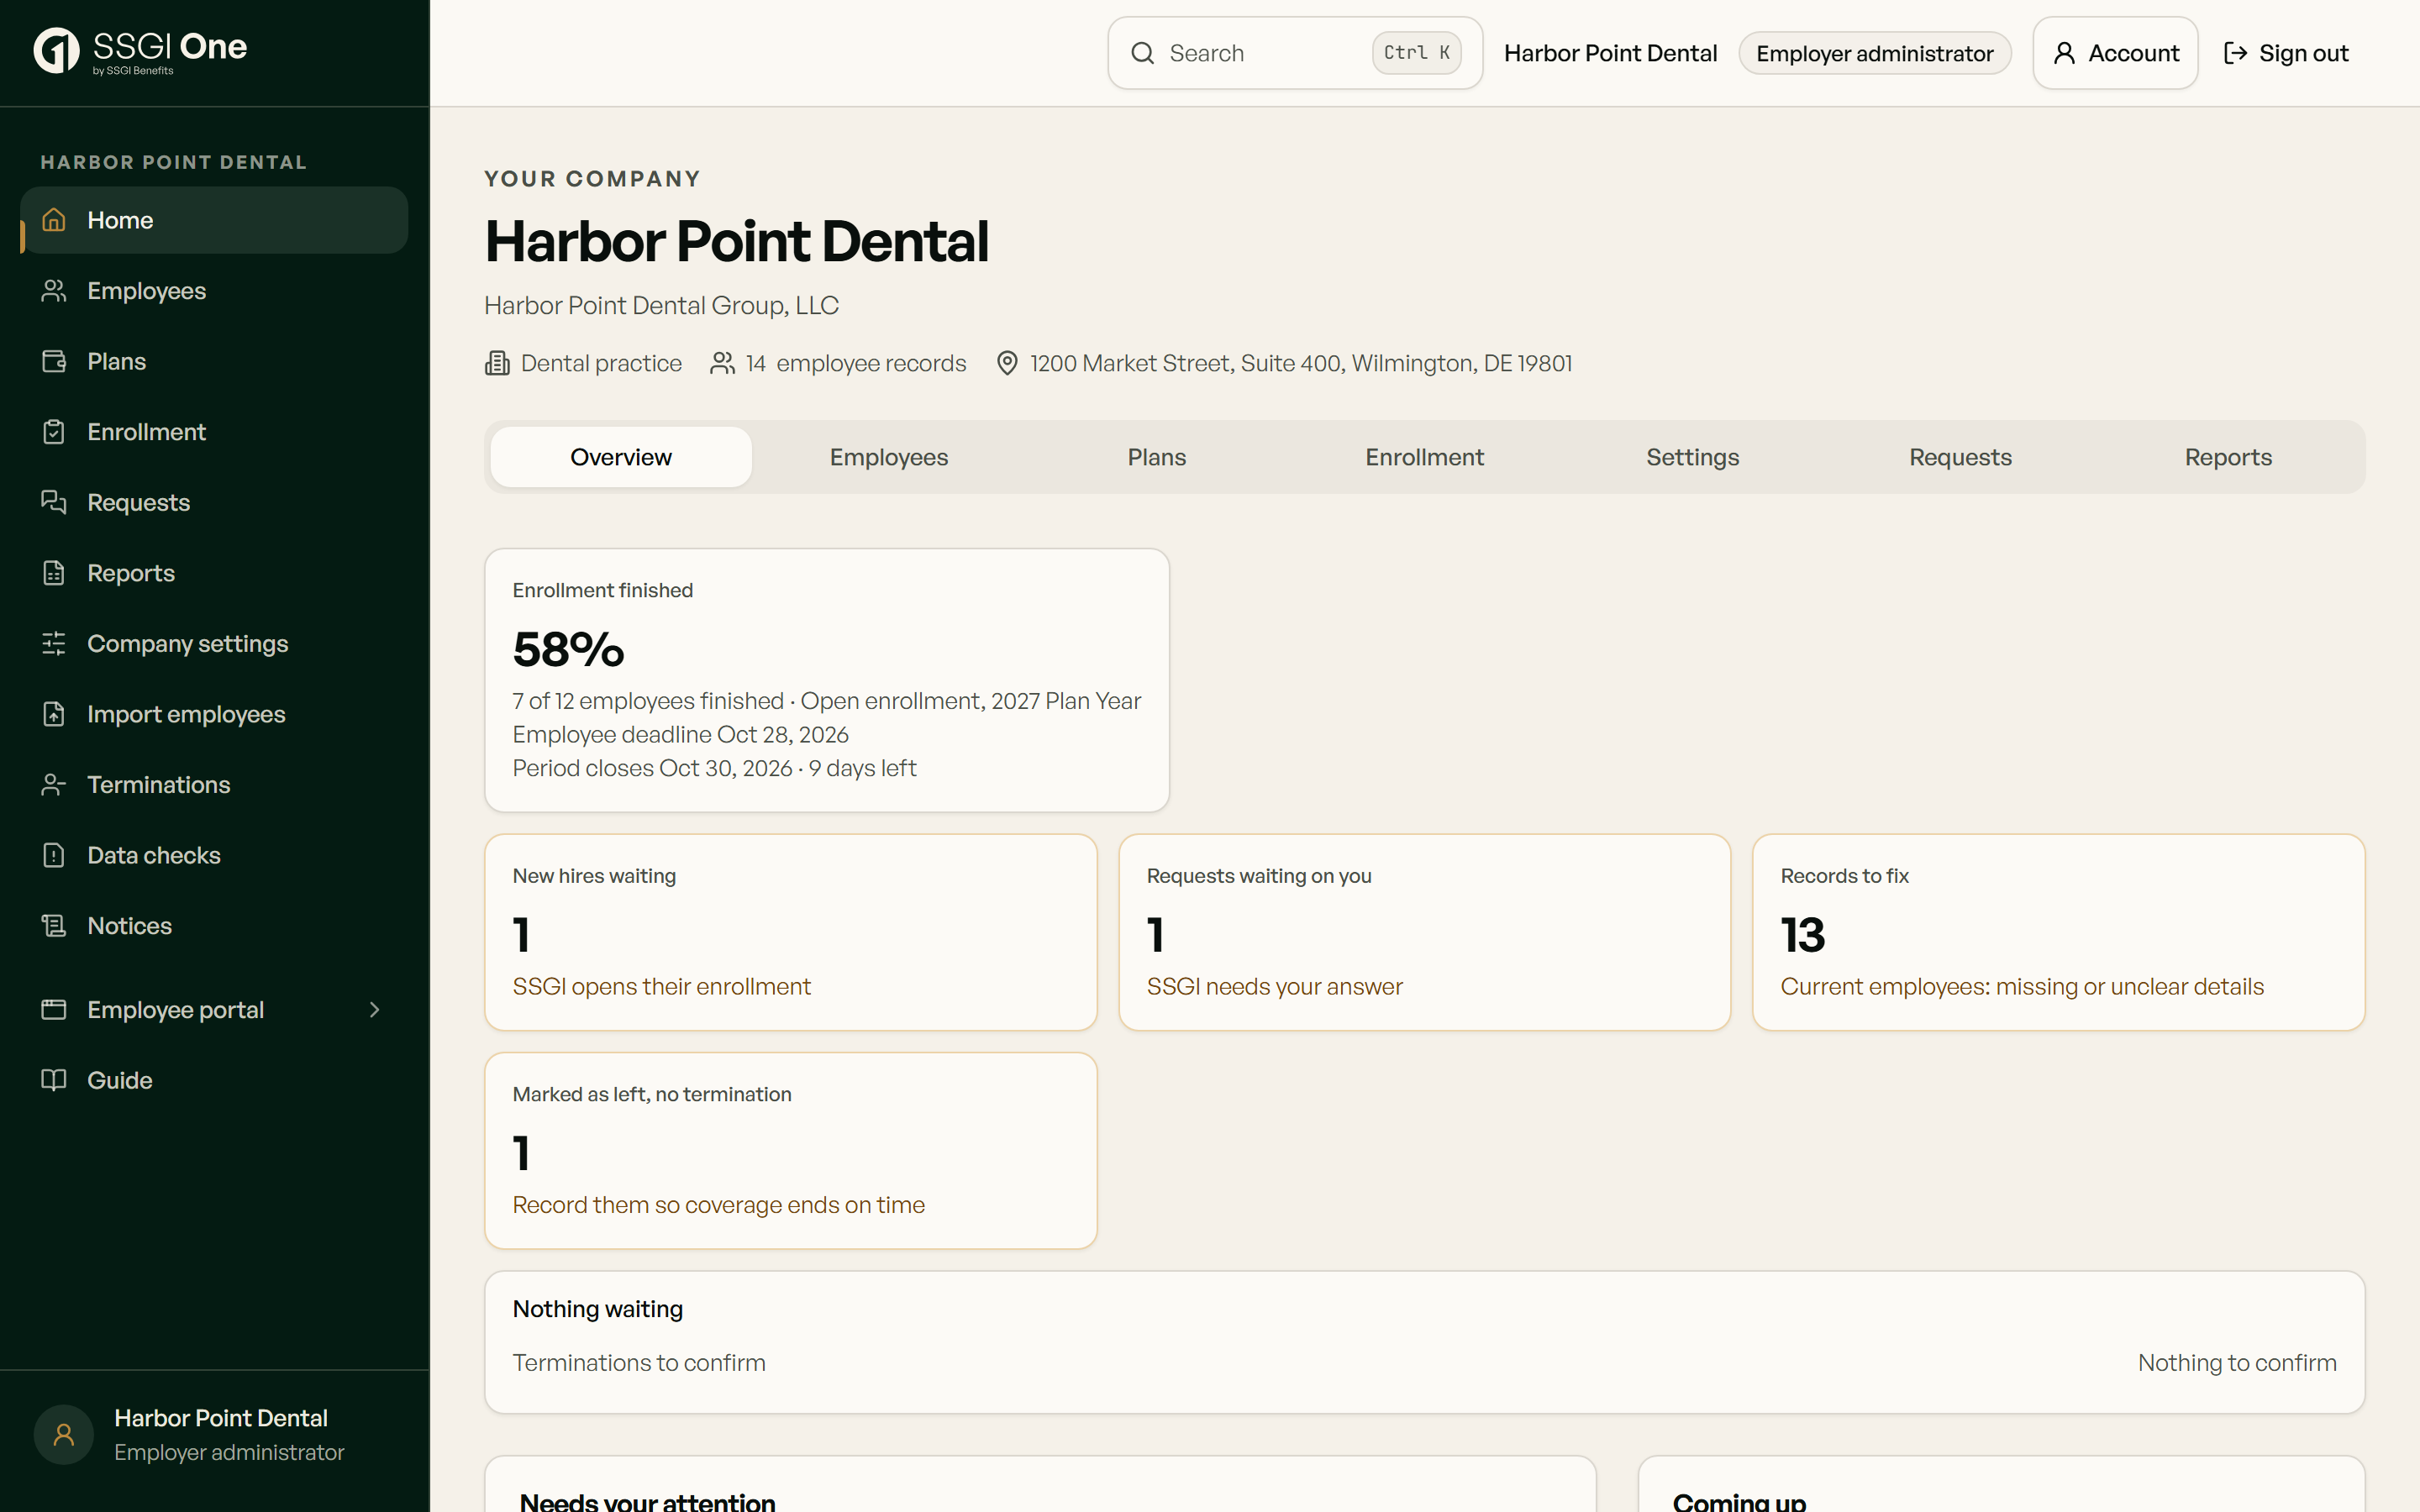
Choosing benefits is the beginning. SSGI connects your benefits strategy with an employer workspace, employee enrollment and a shared place to ask for help throughout the year.
01
For HR
See enrollment progress, employee records and requests that need your attention.
02
For employees
Find coverage information, enrollment steps and a direct route to the SSGI team.
03
For your organization
Discuss your locations, workforce and optional AI integrations as part of the implementation plan.
An actual employer workspace showing example enrollment progress and next steps. Illustrative view · fictional sample data. Select the screen to view it in full.
Frequently asked questions
Straight answers before the first employer review
General education only. Plan availability, pricing, eligibility, funding, networks, and recommendations depend on current employer and market facts.
Complete product coverage
Explore the rest of your benefits program
Find the coverage, funding and service guidance that fits your next decision.
Product availability, eligibility, underwriting, pricing, networks, funding, and recommendations depend on the employer, workforce, jurisdiction, carrier, and current market. SSGI coordinates with carriers, administrators, payroll providers, and the employer's legal and tax advisers; those parties retain their own responsibilities and authoritative records.
Educational information only; not legal, tax, accounting, medical, coverage, actuarial, or compliance advice. Use our contact form for general business information only. Do not include personal health information, claims details, Social Security numbers, member IDs, financial information, or credentials.
Published and maintained by SSGI Benefits, the employee-benefits division of Strategic Sequoia Group Inc. Last reviewed August 24, 2026 using the official sources linked on this page. Carrier availability, eligibility, rates, and recommendations vary by employer and market. This page provides general information and does not constitute legal or tax advice. Meet SSGI leadership · View licensing information.
Map the medical plan, accounts, payroll, and administration together
Begin with employer size, current medical coverage, existing Section 125 or reimbursement documents, administrator, payroll cycle, and the business objective. Keep employee medical, claims, and account information out of the public form.