Health-plan funding strategies

Compare health-plan funding options

SSGI helps employers compare how each funding structure allocates claims risk, cash flow, administration, data access, stop-loss protection, and renewal responsibility. No model is automatically cheaper or better; the right evaluation uses the employer's size, claims credibility, risk tolerance, workforce, reserves, compliance capacity, and current market options.

Risk architecture

Funding is a risk decision—not a marketing label

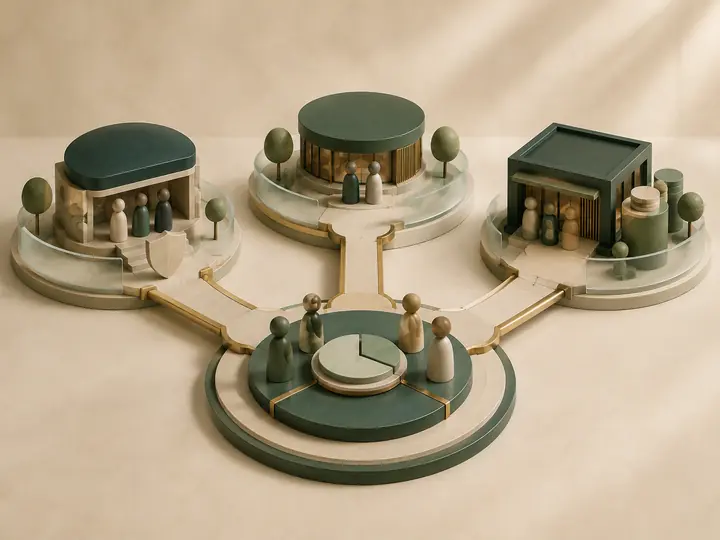
3 funding paths
Three equal health-plan funding paths extending from one comparison table.

A fully insured carrier generally assumes covered claims risk for a fixed premium. A level-funded arrangement commonly combines predictable monthly payments with self-funded mechanics and stop-loss. A self-funded employer assumes claims risk directly, usually with a TPA and stop-loss. Contract details, state rules, claim liability, terminal provisions, fees, and reconciliation can materially change the comparison.

Compare the structure, then the details

Explore the funding trade-offs.

Choose two or three approaches and a discussion priority. Compare how responsibility, budgeting and administration differ before reviewing actual plan terms with your advisor.

Choose up to three approaches

Compare the full annual obligation, payment timing and renewal exposure, including fees and costs outside the quoted payment.

Group insurance

Fully insured

Claims and coverage
The employer pays premiums to an insurer that bears covered claims risk under the insurance contract.
Budgeting
Premiums provide the agreed payment structure during the contract term; renewal terms and rates can change.
Administration
Review plan options, eligibility, enrollment and employee support with the carrier and benefits team.

Ask your advisor: What is included in the premium, and how do the network, plan terms and renewal terms fit our workforce?

Explore fully insured
Self-funded arrangement

Level-funded

Claims and coverage
The employer retains claims obligations. Stop-loss coverage is subject to exclusions, limits and reimbursement terms.
Budgeting
A typical set payment includes estimated claims, administration and stop-loss. Any refund or additional obligation depends on the contracts.
Administration
Review claims administration, reporting duties, stop-loss alignment and obligations at renewal or termination.

Ask your advisor: What is our contractual exposure, and what happens to unpaid claims, refunds and stop-loss when we leave?

Explore level-funded

Educational comparison only. It does not select a suitable plan, calculate savings, establish eligibility or confirm availability. Plan, stop-loss and reimbursement terms need an individual review. Your selections are not sent to SSGI.

Source notes · checked October 27, 2026
Benefits beyond the renewal

A service team and a platform your people can use.

Choosing benefits is the beginning. SSGI connects your benefits strategy with an employer workspace, employee enrollment and a shared place to ask for help throughout the year.

  1. For HR

    See enrollment progress, employee records and requests that need your attention.

  2. For employees

    Find coverage information, enrollment steps and a direct route to the SSGI team.

  3. For your organization

    Discuss your locations, workforce and optional AI integrations as part of the implementation plan.

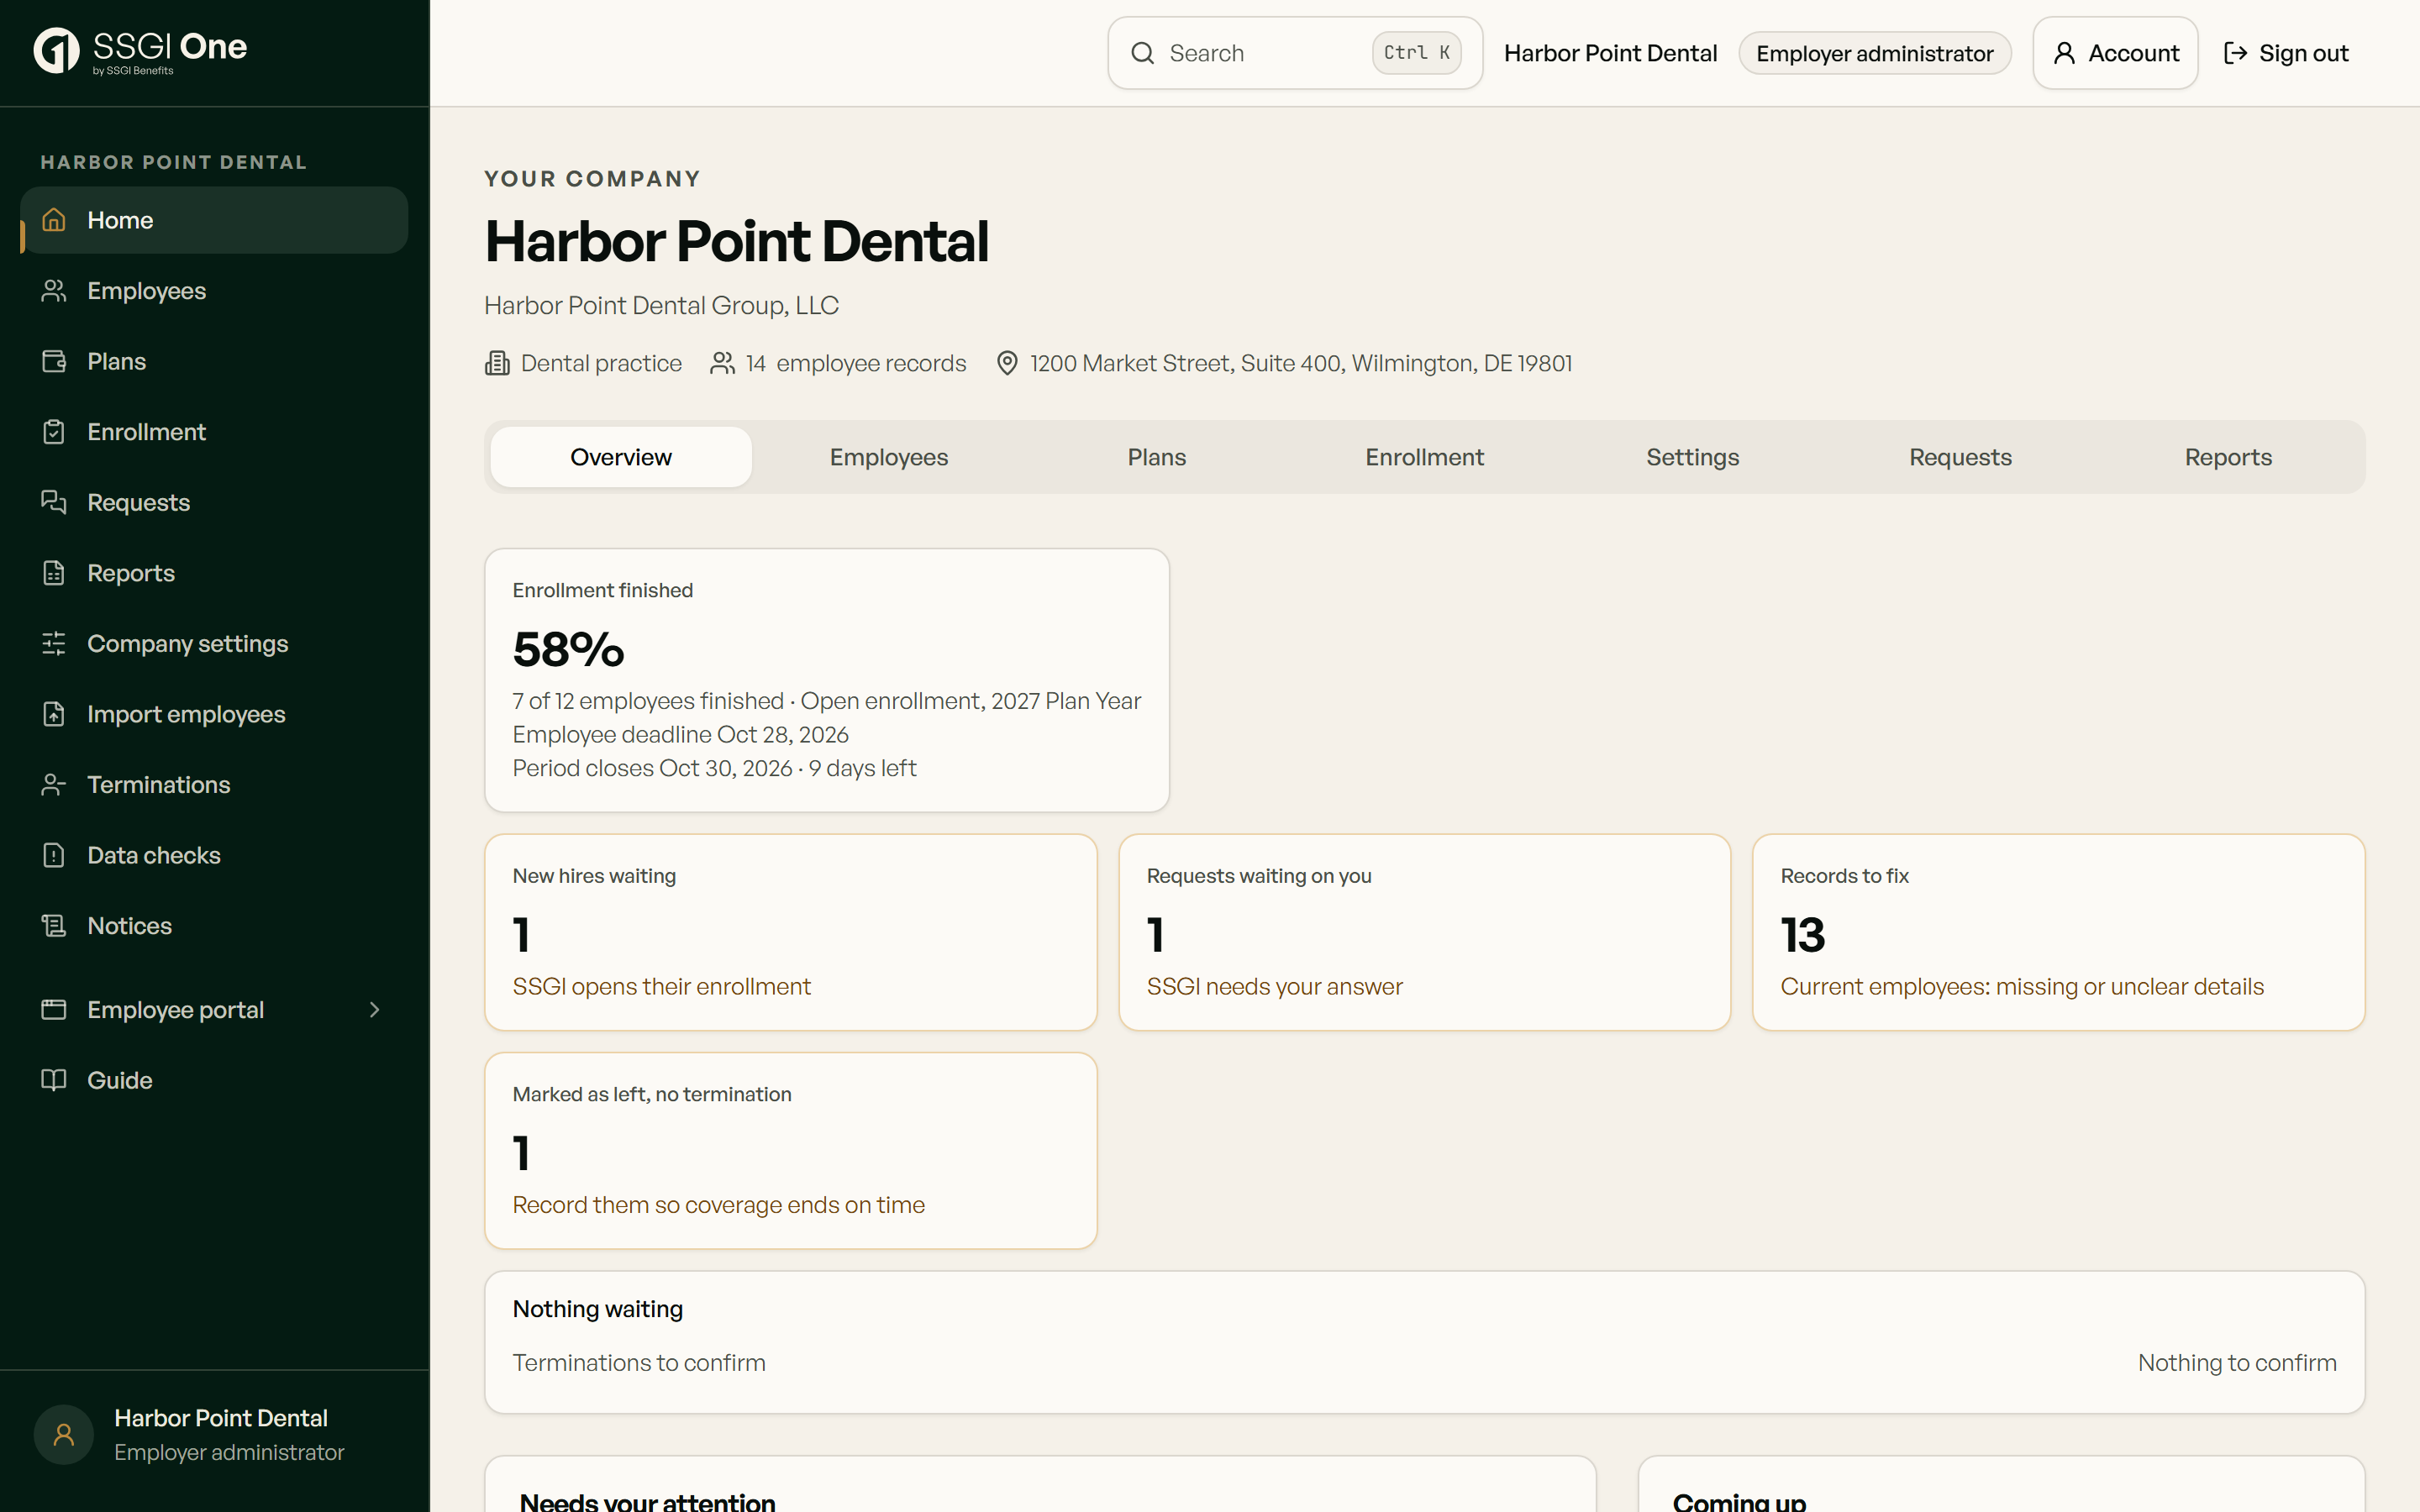
SSGI One preview
SSGI One employer overview showing fictional Harbor Point Dental data
An actual employer workspace showing example enrollment progress and next steps. Illustrative view · fictional sample data. Select the screen to view it in full.
Core facts

What you should know

  • Self-funded and level-funded are alternative health plan funding models.
  • The page is educational guidance for employers.

See how carriers describe carrier case studies on the resource center.

Funding models

How the three primary structures differ

The governing contracts and current proposal control. Labels alone do not reveal maximum liability, exclusions, data rights, or renewal mechanics.

  • Fully insured

    The employer pays a carrier premium and the carrier assumes covered claims risk under the policy. State insurance rules, premium taxes, carrier retention, network, and renewal pricing remain part of the decision.

  • Level-funded

    The employer usually pays a level monthly amount covering estimated claims, stop-loss, and administration. Understand aggregate and specific stop-loss, claim funding, runout, terminal liability, surplus treatment, and renewal calculation.

  • Self-funded

    The employer funds covered claims and engages administrators and networks, commonly purchasing stop-loss to limit specified risk. Cash flow, reserves, fiduciary duties, documents, reporting, privacy, and vendor governance require real operational capacity.

  • Stop-loss protection

    Specific and aggregate stop-loss generally protects the employer—not individual employees—from defined claim risk above contract thresholds. Lasers, exclusions, contract basis, run-in/runout, disclosure, and renewal terms matter.

Due diligence

Questions to answer before changing funding

A proposal should be tested under favorable, expected, and adverse scenarios—not judged by the first monthly payment alone.

Maximum annual liability

Identify the employer's maximum contractual exposure, monthly cash-flow requirements, stop-loss attachment points, exclusions, fees, and any liability extending beyond the plan year.

Claims data and credibility

Determine what credible claims, large-claim, demographic, and utilization information is available and how much weight it can reasonably carry for the group size.

Administration and compliance

Assign plan-document, eligibility, COBRA, claims, appeals, notices, reporting, privacy, fiduciary, and vendor-oversight responsibilities before implementation.

Employee disruption

Compare networks, formularies, plan designs, member services, ID cards, claims processes, and communications so a funding change is not mistaken for a benefit guarantee.

Renewal and exit provisions

Understand renewal methodology, stop-loss renewal, claims runout, terminal funding, data access, contract termination, and the practical path back to another arrangement.

Complete product coverage

Connect the local or strategic decision to the complete benefits portfolio

Medical, supporting benefits, funding, accounts, administration, ICHRA, and leave coordination should work as one program. Compare each category to build a complete, coordinated program for your team.

Product availability, eligibility, underwriting, pricing, networks, funding, and recommendations depend on the employer, workforce, jurisdiction, carrier, and current market. SSGI coordinates with carriers, administrators, payroll providers, and the employer's legal and tax advisers; those parties retain their own responsibilities and authoritative records.

Frequently asked questions

Straight answers before the first employer review

General education only. Plan availability, pricing, eligibility, funding, networks, and recommendations depend on current employer and market facts.

Related guidance

Continue through the SSGI coverage center

Continue exploring the coverage options and decisions that matter most to your team.

Educational information only; not legal, tax, accounting, medical, coverage, actuarial, or compliance advice. Use this form for general business information only. Do not include personal health information, claims details, Social Security numbers, member IDs, financial information, or credentials.

Sources

About this guidance

Published and maintained by SSGI Benefits, the employee-benefits division of Strategic Sequoia Group Inc. Last reviewed August 24, 2026 using the official sources linked on this page. Carrier availability, eligibility, rates, and recommendations vary by employer and market. This page provides general information and does not constitute legal or tax advice. Meet SSGI leadership · View licensing information.

Compare maximum risk, administration, and employee impact before price

Bring the current renewal, census-level business facts, available aggregate reporting, plan documents, fees, and leadership's risk and cash-flow parameters. Do not send claims or employee health information through the public form.