
Carrier comparison
CareFirst vs. Kaiser for Maryland employers
Compare the exact plan and network, then test provider access, care away from home, prescriptions and total employee cost.
Jump to the comparisonThe short answer
Start with the proposed product, network and plan year. CareFirst and Kaiser Permanente each offer more than one plan design, so the carrier name alone cannot settle the decision. Build the comparison around where employees live, the care they need to keep, the cost they would pay and the work required to implement the plan. Use the current proposal, provider directory, pharmacy information and coverage documents together.
Planning a Maryland renewal or carrier change? Start with where your employees need care and the proposals available to your business. Request an employer benefits review.
CARRIER COMPARISON · MARYLAND EMPLOYERS
Compare the structures before the products
Two different access models. Equal consideration. The exact proposal and plan documents control.
Compare the named product as well as the model. CareFirst offers different HMO, POS and PPO designs; Kaiser’s 2026 Maryland small-group documents also include HMO and POS options. Routine care away from home depends on the selected product and its coverage terms.
CareFirst
CONTRACTED-NETWORK MODEL
Workforce needs start here
Contracts connect members to providers
- Independent physicians
- Hospitals + facilities
- Pharmacy network
Kaiser Permanente
INTEGRATED PLAN + CARE DELIVERY
Workforce needs start here
Plan and care delivery coordinate together
- Clinicians · facilities · pharmacy · coordinated records
Compare what matters
- Geography
- Providers
- Prescriptions
- Plan design
- Current plan documents
Neither model is universally better. Fit depends on the workforce, service area, and current-year proposal.
What to carry into the decision
Review these points first, then read the sections and official sources before acting.
- CareFirst and Kaiser use meaningfully different network and care-delivery models; compare the models before comparing copays.
- Employee ZIP codes, current providers, prescriptions, ongoing care, travel, and dependent locations determine disruption.
- A dual-carrier strategy can improve choice for some employers but adds contribution, participation, enrollment, billing, and communication complexity.
- The exact plan, network, contract, and current-year proposal control; neither carrier is universally better.
- Employees need a plain-language explanation of how they find care, obtain prescriptions, use urgent or emergency care, and get help.
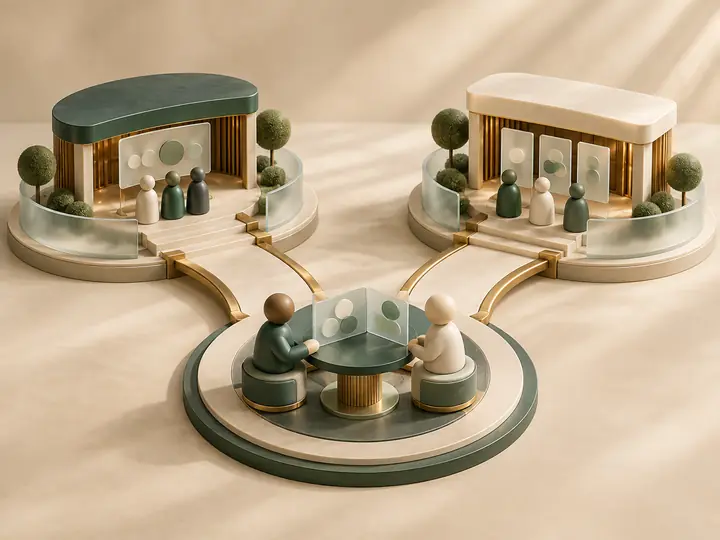
Compare the structures before the individual products
2026 small-group examples illustrate product differences. This is a decision framework, not a quote or coverage determination. Confirm the applicable plan year, proposal, network and coverage documents.
Care model
- CareFirst
- Identify the quoted HMO, POS or PPO product and its named network. The 2026 small-group guide distinguishes regional and national access by product.
- Kaiser Permanente
- Identify the quoted Select or Signature product and its plan design. Maryland's 2026 small-group document library includes HMO and POS options.
- Employer check
- Put the product name, network, effective date and governing documents at the top of the worksheet.
Geography
- CareFirst
- Check routine care outside the local area against the proposed network and product rules.
- Kaiser Permanente
- Separate emergency and urgent care provisions from any routine out-of-plan benefits in the proposed product.
- Employer check
- Test employees living outside the area, remote workers and dependents away at school. Do not assume one carrier-wide rule.
Provider choice
- CareFirst
- Check the exact network rather than relying on the CareFirst name on a practice website.
- Kaiser Permanente
- Confirm the relevant clinicians, facilities and any referral or out-of-plan conditions for the selected product.
- Employer check
- Arrange an appropriate secure provider review before deciding; keep personal medical details out of public planning tools.
Prescriptions
- CareFirst
- Use the proposal's pharmacy coverage and current drug information.
- Kaiser Permanente
- Use the selected plan's formulary, pharmacy access and authorization rules.
- Employer check
- Verify the specific medication, tier, pharmacy and any authorization or specialty requirements through a secure process.
Total cost and contributions
- CareFirst
- Compare the actual quoted premium and benefit design.
- Kaiser Permanente
- Compare the actual quoted premium and benefit design.
- Employer check
- Model employer spending, payroll deductions, deductible exposure and out-of-pocket limits using the same employee tiers and assumptions.
Administration
- CareFirst
- Confirm the proposal's enrollment, eligibility and billing arrangements.
- Kaiser Permanente
- Confirm the proposal's enrollment, eligibility and billing arrangements.
- Employer check
- Name the owners of enrollment, payroll changes, employee communication and the first invoice review.
1. Begin with employee geography
List workforce counts by general region, then flag employees who live outside the main area. Compare routine care, emergency care and dependent access separately. A service-area requirement and an away-from-home benefit answer different questions.
2. Measure provider and prescription disruption
Request a secure review of the providers and medications employees need to keep. Use exact product and network names. Record unresolved items and the date checked; a directory result is an input to verification, not a guarantee of every service.
- Start with the exact network and plan year in each proposal. Check each important provider at the location employees use, then confirm participation and new-patient availability with the provider and carrier.
- Use the formulary that matches the employer's group size, funding arrangement, and plan. CareFirst separates drug lists by funding and year; Kaiser lists distinct small-employer, large-employer, and other plan formularies.
- For priority prescriptions, verify the drug, strength, tier, pharmacy access, and any prior authorization, step therapy, or quantity limits. Resolve ongoing-treatment and transition-of-care questions before employees enroll.
3. Compare the care experience
Walk through practical scenarios: booking primary care, seeing a specialist, filling a recurring prescription and seeking care away from home. For a POS proposal, examine the conditions and employee costs for out-of-plan care rather than treating it as unrestricted access.
4. Compare plan design and employer contribution
Use the same census, coverage tiers and employer contribution assumptions for each proposal. Show payroll deductions beside deductibles and out-of-pocket limits. A premium difference alone does not describe the employee's financial experience.
5. Evaluate a dual-carrier strategy carefully
If offering both is under consideration, verify that the actual proposals permit the arrangement and meet participation and contribution conditions. Assign ownership of eligibility, payroll, billing and employee guidance before treating additional choice as an improvement.
6. Review the decision every year
Recheck employee locations, proposed networks, provider access, contribution strategy and implementation issues at renewal. The documents cited here are 2026 examples; confirm the applicable plan year before making a decision.
Related guidance
Continue to the service or decision that best fits your situation.
Sources
- CareFirst 2026 small-group health plan guide2026 small-group product and regional/national network distinctions; confirm the actual proposal.
- Kaiser Permanente Mid-Atlantic small-group plan documentsOfficial Maryland Select and Signature HMO and POS sample document listings.
- Kaiser Permanente Maryland2026 Select traditional HMO sample2026 Maryland sample evidence of coverage; actual current plan documents control.
- Kaiser Permanente Maryland2026 Select POS sample2026 Maryland sample evidence of coverage; actual current plan documents control.
- CareFirst — Employer Health PlansOfficial CareFirst employer overview and service-area disclosure.
- Kaiser Permanente Business — Employer Health PlansOfficial Kaiser Permanente employer-plan portal.
- CareFirst — Find a DoctorSelect the network attached to the actual employer proposal.
- CareFirst — Employer Drug SearchOfficial formularies organized by funding arrangement and plan year.
- Kaiser Permanente — Mid-Atlantic Doctors and LocationsOfficial Maryland, Virginia, and Washington, DC provider and facility lookup.
- Kaiser Permanente — Mid-Atlantic Drug FormularyMatch the formulary to the employer's specific plan and group category.
- U.S. Department of Labor — Health PlansOfficial EBSA resources for employer health-plan administration and compliance.
Educational information only; not legal, tax, accounting, actuarial, medical, coverage, investment, or compliance advice. Product availability, eligibility, underwriting, pricing, networks, plan terms, and recommendations depend on current facts. Use the contact form for general business information only. Do not include personal health information, claims details, Social Security numbers, member IDs, financial information, or credentials.
Run the CareFirst–Kaiser comparison on your workforce
Tell us your company size, employee locations, and renewal month. SSGI can help you frame a comparison of the current proposals. Share business information only; keep employee health and claims information out of this form.