Build a connected package of dental, vision, life, disability and voluntary benefits alongside medical coverage. Available options depend on your group, state and carrier rules.
SSGI helps employers organize the benefits that sit beside medical coverage: group dental and vision, employer-paid and voluntary life and AD&D, short- and long-term disability, accident, critical illness, hospital indemnity, and other worksite benefits. The goal is a coherent portfolio employees can understand—not a stack of disconnected policies. SSGI compares the available carriers and plan designs in the current market; availability, appointments, underwriting, pricing, state, employer, and group-size rules vary.
Portfolio design
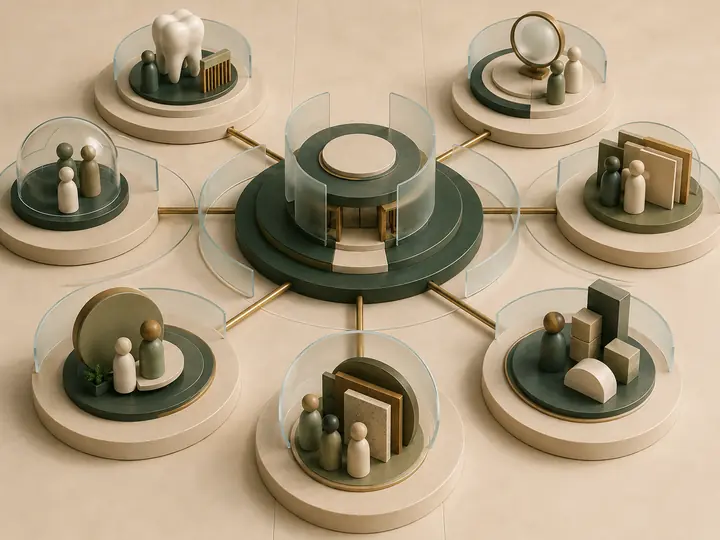
Supporting benefits influence how employees experience the whole program
Core + supporting
01Dental
02Vision
03Life
04Disability
05Supplemental
06Voluntary
Medical coverage may anchor the package, but income protection, dental, vision, life, and voluntary choices often determine whether employees view the program as complete. SSGI compares eligibility, funding, enrollment, portability, evidence-of-insurability, payroll, communication, and administration before a product is added.
From invitation to enrollment
Make the next step easy to find.
Employees open their SSGI One invitation, sign in and follow the enrollment steps for their employer. New hires, enrollment windows, life-event requests and waivers belong in the same experience.
Direct carrier appointments for supporting benefits
SSGI maintains direct appointments with the insurance carriers it represents. Appointment creates access to evaluate and place eligible coverage; it does not make any carrier an automatic recommendation. Carrier and product availability varies by state, service area, employer, group size, participation, underwriting, and effective date.
This is a representative—not exhaustive—list. SSGI works with many other carriers and benefits-market partners based on the employer, state, product, group size, underwriting, and effective date.
Dental & Vision
Dental and vision
Direct relationships used to compare dental and vision networks, plan design, orthodontia, waiting periods, exam and lens allowances, and claims when those products fit the employer's workforce and plan design.
Guardian
VSP Vision Care
United Concordia Dental
Dominion National
Versant Health
Dearborn Group
Life · Disability · Voluntary · Supplemental · Specialty
Life, disability, voluntary, supplemental, and specialty
Direct relationships used to compare life, AD&D, short- and long-term disability, voluntary and worksite, accident, critical illness, hospital indemnity, and other supplemental options when those products fit the employer's workforce and plan design.
The Hartford
Mutual of Omaha
Principal
Humana
Sun Life
MetLife
Trustmark
Aflac
Companion Life Insurance Company
Bankers Life
Lincoln Financial Group
Reliance Standard
Unum
Category placement is for navigation only and is not a limitation on a carrier's products. A carrier may span products without duplicate cards.
Benefits and market-access partners
Additional support where appropriate
The organizations below are benefits and market-access partners—not insurance carriers. SSGI may use these relationships where appropriate while maintaining direct carrier appointments. The precise role varies by case and product; none of these organizations endorses SSGI.
General-agency and wholesale relationships
Wholesale and general agencies that support market placement, quoting workflow, and case support where appropriate.
CRC Benefits
Wholesale general agency
Used where appropriate for market placement, quoting workflow, and case support.
Emerson Rogers
General agency
Used where appropriate for market placement, quoting workflow, and case support.
Amwins
Wholesale general agency
Used where appropriate for market placement, quoting workflow, and case support.
Benefits, administration, network, and market-access relationships
Other benefits, administration, network, or market-access relationships used where appropriate. The precise role varies by case and product.
Benecon
Benefits and administration
Used where appropriate for benefits administration and market access.
Careington Benefits Solutions
Network and benefits solutions
Used where appropriate for network and benefits solutions.
Kelly Benefits
Benefits administration and market access
Used where appropriate for benefits administration and market access.
CRC Benefits and Emerson Rogers are general agencies—not insurance carriers. SSGI may use these relationships where appropriate while maintaining direct carrier appointments.
Coverage portfolio
Every major ancillary and voluntary category
SSGI compares the available carriers and plan designs in the current market. Availability, appointments, underwriting, pricing, state, employer, and group-size rules vary, so each category is evaluated as part of one program rather than a standalone brochure.
Group dental insurance
Compare preventive, basic, and major-service designs; annual maximums; waiting periods; networks; orthodontia; employer contributions; and voluntary options.
Group vision insurance
Review exams, lenses, frames, contacts, frequency limits, networks, allowances, and whether employer-paid or voluntary funding fits the workforce.
Group life and AD&D
Coordinate basic employer-paid life, accidental death and dismemberment, supplemental employee and dependent elections, beneficiary education, and evidence-of-insurability rules.
Short- and long-term disability
Evaluate benefit percentages, elimination periods, maximum durations, definitions of disability, offsets, employer-paid versus voluntary funding, and leave-program coordination.
Accident, critical illness, and hospital indemnity
Explain limited-benefit products clearly, including covered events, benefit schedules, exclusions, portability, payroll deductions, and how these policies differ from medical insurance.
Voluntary and worksite benefits
Build an enrollment strategy that adds employee choice without overwhelming people or creating avoidable payroll and administration friction.
Program design
Decisions that matter beyond the product list
A good ancillary program is selected and implemented as an operating system, not as a collection of brochures.
Employer-paid versus voluntary
Model the recruiting, participation, tax, and budget implications of employer-paid core benefits, voluntary elections, or a blended contribution approach.
Enrollment and evidence rules
Plan initial eligibility, guaranteed-issue windows, late-entrant rules, evidence-of-insurability workflows, dependent elections, and annual enrollment communications.
Payroll and administration
Confirm deduction frequencies, after-tax or pre-tax treatment where applicable, file ownership, eligibility feeds, billing reconciliation, and termination handling.
Employee education
Use plain language to distinguish medical insurance from limited-benefit products and explain what each policy does, does not do, and how claims are submitted.
Complete product coverage
Connect the local or strategic decision to the complete benefits portfolio
Medical, supporting benefits, funding, accounts, administration, ICHRA, and leave coordination should work as one program. Compare each category to build a complete, coordinated program for your team.
Product availability, eligibility, underwriting, pricing, networks, funding, and recommendations depend on the employer, workforce, jurisdiction, carrier, and current market. SSGI coordinates with carriers, administrators, payroll providers, and the employer's legal and tax advisers; those parties retain their own responsibilities and authoritative records.
Frequently asked questions
Straight answers before the first employer review
General education only. Plan availability, pricing, eligibility, funding, networks, and recommendations depend on current employer and market facts.
Related guidance
Continue through the SSGI coverage center
Continue exploring the coverage options and decisions that matter most to your team.
Educational information only; not legal, tax, accounting, medical, coverage, actuarial, or compliance advice. Use this form for general business information only. Do not include personal health information, claims details, Social Security numbers, member IDs, financial information, or credentials.
Published and maintained by SSGI Benefits, the employee-benefits division of Strategic Sequoia Group Inc. Last reviewed August 24, 2026 using the official sources linked on this page. Carrier availability, eligibility, rates, and recommendations vary by employer and market. This page provides general information and does not constitute legal or tax advice. Meet SSGI leadership · View licensing information.
Review the full benefits package—not only medical renewal
Start with the current products, employer contributions, participation, payroll setup, enrollment process, and the protection gaps employees are asking about. Do not send employee health, claims, or identifying information through the public form.