Maryland FAMLI filing is open through Nov. 15, 2026.

FAMLI guide
ICHRA / CHOICE Arrangements

Does ICHRA fit your workforce?

Compare individual coverage with your group plan. SSGI helps you evaluate workforce fit, contribution costs and employee choice before you make a change.

  • Workforce fit
  • Cost comparison
  • Enrollment planning

Balanced evaluation

Compare the fit before choosing a path

2 paths
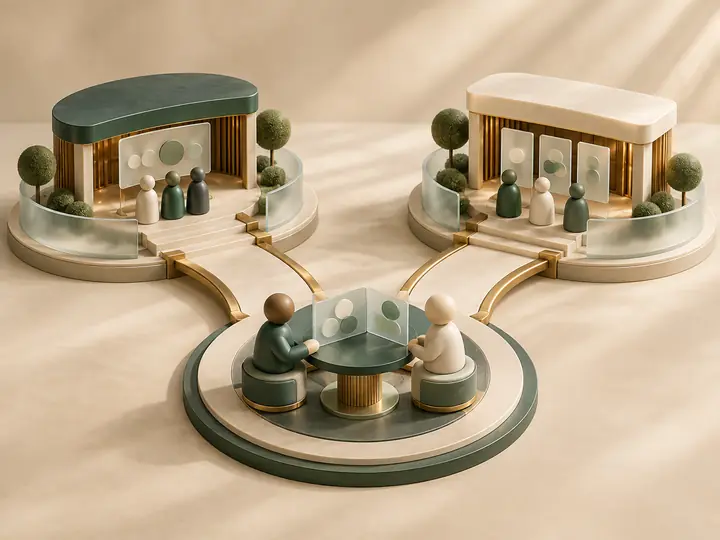
Two equally sized benefits pavilions connected to an advisory table.

Group plan

Shared plan and carrier structure

ICHRA

Defined contribution and individual choice

Neither path is the automatic winner; workforce, market, budget, and administration determine fit.

The fit framework

Find the right fit for your workforce.

Explore each factor to think through whether ICHRA fits your workforce. This is an informational framework — it does not store anything you read and it is not a legal determination.

Workforce

Who are you covering, and how diverse are their needs?

ICHRA tends to fit best when a workforce spans different life stages, geographies, or coverage needs — and less well when everyone wants the same plan.

  • A workforce with varied ages, family sizes, or health needs can benefit from individual choice.
  • A workforce that prefers one shared plan and network may prefer a traditional group plan.
  • Federal rules allow certain employee classes — including full-time, part-time, seasonal, salaried or hourly, and employees in the same rating area — subject to class-size and other requirements.
Side by side

Traditional group plan vs ICHRA

A concise comparison across the dimensions that matter most. Neither path is universally better — the right choice depends on your workforce and goals.

  • Cost structure

    Traditional group plan
    Defined benefit; employer and often employees share a negotiated premium.
    ICHRA
    Defined contribution; employer sets a fixed, tax-advantaged amount per employee.
  • Annual cost movement

    Traditional group plan
    Renewal pricing varies by market and funding arrangement; ACA-compliant small-group premiums do not use employees’ health history.
    ICHRA
    Contributions are set by the employer and held to a budget you control.
  • Employee choice

    Traditional group plan
    Employees select from the plans the employer offers — usually one or two.
    ICHRA
    Employees use the contribution to shop the individual market for the plan that fits them.
  • Network & providers

    Traditional group plan
    Network is fixed by the chosen group plan; breadth depends on the carrier.
    ICHRA
    Network depends on the qualifying individual plan each employee selects, on or off the Marketplace.
  • Administration

    Traditional group plan
    Employer coordinates eligibility, enrollment and renewals; the carrier or administrator handles claims.
    ICHRA
    Employer arranges reimbursement processing, substantiation and compliance, internally or with qualified administration support.
  • May fit when

    Traditional group plan
    Your workforce wants one shared plan, a carrier-managed experience, and predictable carrier handling of enrollment and claims.
    ICHRA
    Your workforce has varied needs across a strong individual market and values choosing its own coverage.
  • May not fit when

    Traditional group plan
    Your workforce has varied needs the single plan cannot meet, or the local individual market is strong enough that choice would lower total cost.
    ICHRA
    Your workforce prefers one shared plan, the local individual market is thin or expensive, or your team cannot take on added administration.
ICHRA in SSGI One

Make the allowance process easier to follow.

Employees use the same login for group benefits and ICHRA. SSGI One brings allowance acceptance, proof of coverage and reimbursement requests into one place, with status and a route to your SSGI team.

  1. Review and accept the allowance offered by your employer.
  2. Add the requested proof of individual coverage.
  3. Prepare a reimbursement request and follow its status.
  4. Ask your SSGI team when you need help with the next step.

The portal supports the process; eligibility, documentation, plan rules and the agreed administration arrangement still apply. Submitting a request is not a promise of reimbursement.

Terminology and administration update ·

ICHRA, now also known as a CHOICE Arrangement

Federal agencies now use the name CHOICE Arrangement for the employer-funded health benefit commonly known as an Individual Coverage Health Reimbursement Arrangement, or ICHRA.

For employers, the key decision remains whether individual coverage fits their workforce and budget. SSGI helps evaluate employee coverage options, contribution strategies and administration needs alongside traditional group health plans.

Sources: CMS employer guide (opens in a new tab) · SBA announcement (opens in a new tab)
Core facts

What to know about ICHRA

Durable, verified facts about how ICHRA works, who governs it, and what it requires — drawn from official federal sources.

What ICHRA is

ICHRA is an Individual Coverage Health Reimbursement Arrangement. It lets employers fund employees' individual market coverage with a defined, tax-advantaged contribution.

Who governs it

ICHRA is governed by federal rules set by the IRS, the U.S. Department of Labor, and CMS.

How it works

Employers set a fixed contribution per employee; employees use it to shop the individual market for a plan that fits them.

Employee classes

Federal rules allow certain employee classes — including full-time, part-time, seasonal, salaried or hourly, and employees in the same rating area — subject to class-size and other requirements.

Administration

Employers must arrange reimbursement administration and compliance; some handle functions internally, while many use a qualified administration partner. SSGI assesses feasibility and coordinates qualified partners; it is not the reimbursement or claims administrator.

Not a universal winner

ICHRA is not automatically better or lower-cost than a group plan. Fit depends on the individual market, employee classes, contribution design, and administration.

How we evaluate outcomes

An evidence-based approach to outcomes

SSGI evaluates outcomes across cost and funding decisions, administrative workload, employee experience, implementation accuracy, and year-round follow-through. See how we evaluate and share client outcomes.

When ICHRA may deserve evaluation

When ICHRA may deserve evaluation — and when group coverage may remain better

Neither path is a universal winner. ICHRA may deserve a closer look in some situations; a traditional group plan may remain the better choice in others. Use the criteria below to weigh which approach fits your workforce, budget, and market.

ICHRA may deserve evaluation

When the individual market may serve your workforce well

  • Your workforce spans different life stages, geographies, or coverage needs that one group plan cannot meet well.
  • The individual market is strong where your employees live, with broad networks that include their preferred providers.
  • You want a defined, tax-advantaged contribution you can budget across multiple years instead of negotiating annual premiums.
  • Your team can coordinate a qualified ICHRA administration partner for reimbursements and compliance.
Group coverage may remain better

When a traditional group plan may remain the better choice

  • Your workforce prefers one shared plan and network, and a carrier-managed enrollment and claims experience.
  • The individual market is thin or expensive where your employees live, so choice would not lower total cost.
  • Your team cannot take on the added administration ICHRA requires, or you want the carrier to handle eligibility, enrollment, and claims.
  • Renewal predictability through a single negotiated plan matters more than per-employee individual choice.

Read the ICHRA employer decision guide

For a fuller walkthrough of when ICHRA may deserve evaluation and when group coverage may remain better — including the five-factor framework, contribution design, and compliance — read our employer decision guide.

Read the decision guide

Want to know whether an ICHRA comparison could change your renewal math? Request a benefits review and we'll start with your numbers.

Request a Benefits Review
From evaluation to implementation

How an ICHRA review moves forward

A compact path from the first fit question through launch and ongoing support — with licensed people accountable at every step.

Five stages, one accountable path

Connected work. Clear responsibilities.

  1. Employer

    Establish the arrangement, make employer decisions and remain responsible for plan administration and compliance.

  2. SSGI

    Help evaluate fit, compare approaches and coordinate with the selected administration partner and carriers.

  3. Benefits partners

    Provide the agreed administration functions; carriers confirm qualifying coverage and policy terms.

The employer may administer the arrangement internally or use qualified support. SSGI is not the reimbursement administrator.

  1. Evaluate fit
  2. Design contributions
  3. Confirm requirements
  4. Coordinate partners
  5. Launch & support
Licensed people accountable

SSGI coordinates with the ICHRA administration partner and your carriers. We are not the reimbursement administrator ourselves — licensed people stay accountable for every recommendation and decision throughout your review.

Employer questions

Direct answers before the first conversation

Understand your options and the responsibilities behind each decision.

Official sources

Where to verify ICHRA rules

ICHRA is governed by federal rules set by the IRS, the U.S. Department of Labor, and CMS. These six official resources confirm how ICHRA works — the rulemaking, model notice, model attestation, and agency guidance.

Sources

Last verified

Reviewed by Laura Decker, Vice President, Strategic Sequoia Group Inc. .

Request an ICHRA Feasibility Review

We'll show you where ICHRA fits, where it does not, and what the numbers mean for your workforce.